How to Use the Boat Loan Calculator
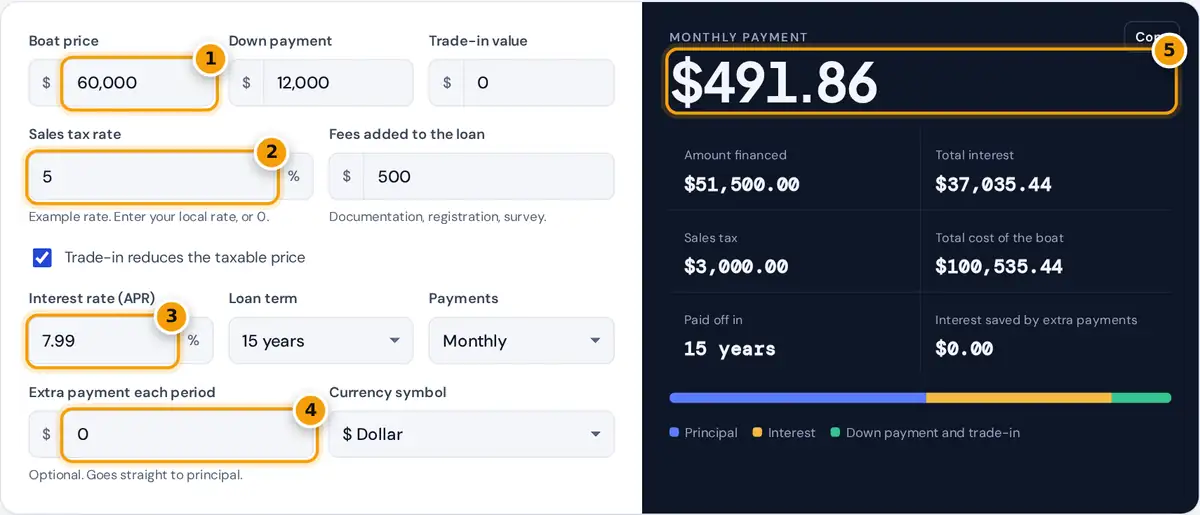
- Enter the boat price, down payment and trade-in value.
- Enter your sales tax rate and fees added to the loan.
- Set the interest rate, term and payment frequency.
- Add an optional extra payment to see interest saved.
- Read the payment, amount financed, interest and total cost.
Enter the price of the boat, your down payment and the value of any boat or vehicle you are trading in. Add the sales tax rate where you will register the boat, or 0 if none applies, and any fees the dealer or lender adds to the loan, such as documentation, registration or a marine survey. In many places a trade-in lowers the taxable price; untick the box if yours does not.
Then enter the interest rate, choose a term and decide how often you will pay. Boat loans often run longer than car loans, with terms of 10 to 20 years on larger boats. The result shows the payment, the amount financed, the total interest and the full cost of the boat. Add an extra payment to see how much sooner the loan ends and how much interest you save.
Boat Loan Payment Formula
periodic rate i = APR ÷ payments per year, n = years × payments per year
payment = L × i ÷ [1 − (1 + i)−n]
Each payment first covers the interest on the remaining balance, and the rest reduces the principal. Early payments are mostly interest, which is why long terms cost so much more. Extra payments go straight to principal, so every later payment carries less interest.
Bi-weekly and weekly options divide the annual rate by 26 or 52 and spread the same term over more, smaller payments.
Worked Example
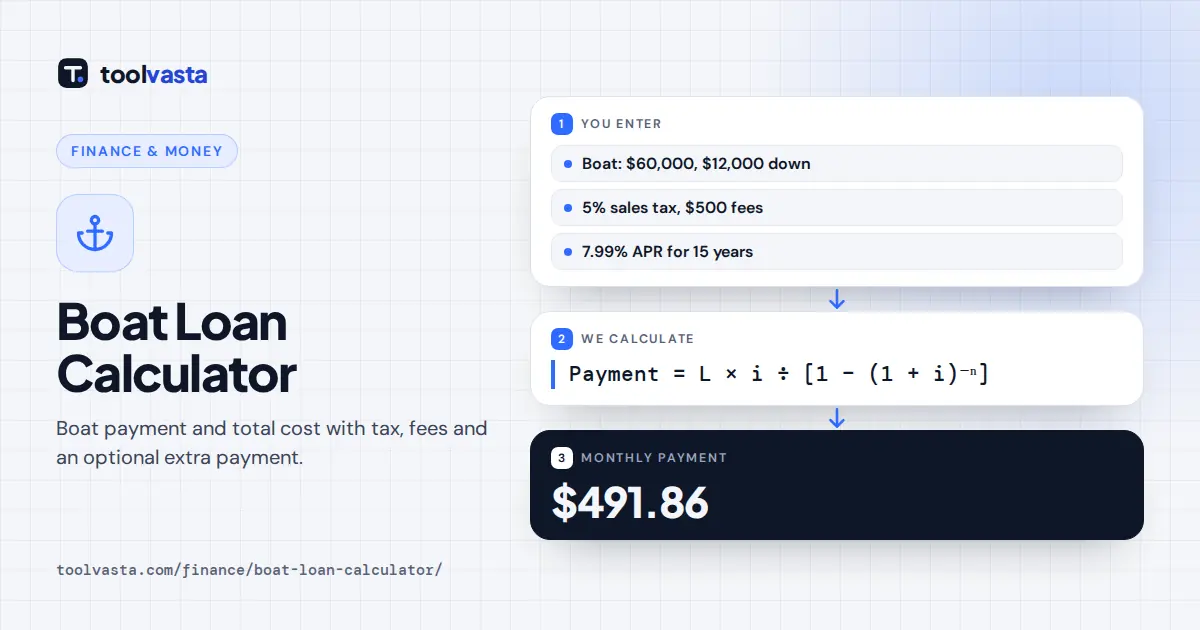
A $60,000 boat with $12,000 down, 5% sales tax and $500 of fees needs $51,500 of financing: the $3,000 of tax and the fees are added to the $48,000 balance. At 7.99% over 15 years the monthly payment is $491.86. You pay $37,035.44 of interest, and the boat costs $100,535.44 in total including the down payment.
Adding $100 a month to each payment pays the loan off in 10 years and 11 months and cuts the interest to $25,734.57, a saving of $11,300.88. Shortening the term has a similar effect, at the cost of a higher required payment.
| Monthly payment per $10,000 borrowed | 10 years | 15 years | 20 years |
|---|---|---|---|
| 6% APR | $111.02 | $84.39 | $71.64 |
| 8% APR | $121.33 | $95.57 | $83.64 |
| 10% APR | $132.15 | $107.46 | $96.50 |
Multiply by the number of tens of thousands you plan to borrow for a quick estimate.
Boat lenders often look at the age, size and type of the boat as well as your credit. Newer boats and larger loans tend to qualify for longer terms, while older boats may be limited to shorter terms or need a larger down payment. Get the actual term and rate from your lender, then use the schedule to see how quickly you build equity compared with the boat's expected resale value.
Tips for Financing a Boat
- Budget for ownership costs as well as the loan: insurance, mooring or storage, maintenance, fuel and winterizing can add a large share of the payment.
- A larger down payment lowers both the payment and the interest, and helps keep the loan below the boat's resale value.
- Ask whether the loan has a prepayment penalty before planning extra payments.
- Get a marine survey on a used boat. Lenders often require one for older or larger boats.
- Compare offers from a dealer, a bank and a credit union using the APR, not only the monthly payment.
Assumptions and Limits
The calculator assumes a fixed rate, equal payments and the first payment one period after the loan starts. Sales tax rules on boats and trade-ins differ by state and province, so enter your own rate and check how a trade-in is treated. Lender fees may be paid upfront instead of financed. Results work in any currency and are estimates, not a loan offer. For a car or truck, try the car payment calculator.
Frequently asked questions
How long can you finance a boat?
Terms depend on the lender and the boat's price and age. Smaller loans often run 5 to 10 years, while larger new boats can be financed for 15 or 20 years. Longer terms lower the payment but raise total interest.
How much down payment do I need for a boat?
Many lenders ask for 10% to 20% down, depending on your credit and the boat. A bigger down payment reduces the loan, the interest and the risk of owing more than the boat is worth.
Is sales tax included in a boat loan?
Often it can be financed, which is how this calculator treats it. Rules differ by state and province, and some places reduce the taxable price by your trade-in. Enter your own rate.
How do extra payments affect a boat loan?
Extra payments reduce the principal directly, so less interest accrues each period and the loan ends sooner. On a 15-year loan, a small extra amount each month can save thousands in interest.
What credit score do I need for a boat loan?
Lenders set their own requirements, and better scores usually get lower rates. Compare offers and use the rate you are quoted in the calculator to see the real payment and interest.
Should I choose monthly or bi-weekly boat payments?
Bi-weekly payments spread the same term into 26 smaller payments a year and can slightly reduce interest. Choose the schedule that matches your pay so payments are never late.